Rs 15L Fees Recovery : 18-Month Analytics MBA vs 2-Year IIMs – Complete Parent ROI Guide
What this article covers
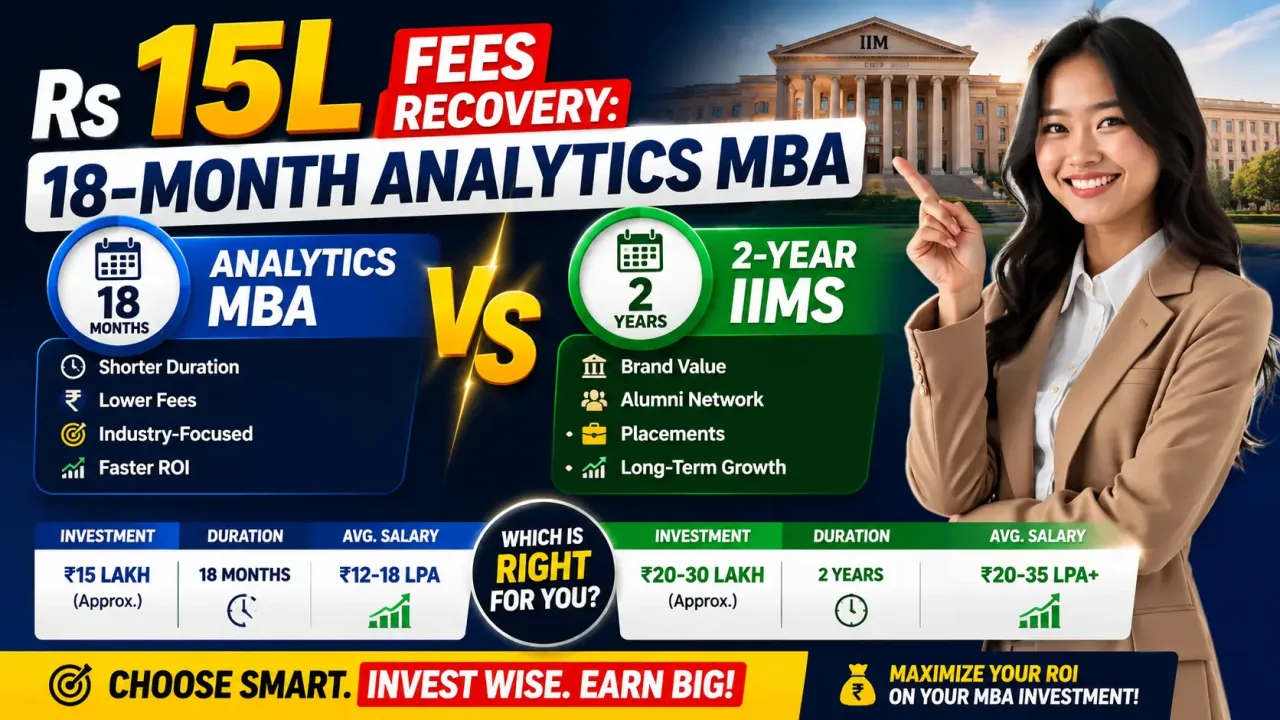
If you're a parent sitting across the table from your child right now, calculator in one hand and a stack of brochures in the other, you already know this decision isn't just about prestige. It's about real money — the kind that takes years to recover, sometimes with interest attached from a bank loan you'll both be tracking closely. And when your child says "IIM" or "Analytics MBA" in the same sentence, it's completely natural to feel a bit lost about which path actually makes financial sense.
So let's put the emotion aside for a moment and look at this purely through the lens every parent genuinely cares about — how long will it actually take to recover the fees, and which path gets there faster with less risk. No sugarcoating, just the real numbers.
Understanding What You're Actually Comparing#
Before diving into numbers, it's worth being clear about what these two paths actually represent, because they're genuinely different animals, not just different durations of the same thing.
A traditional two-year IIM MBA is the flagship, campus-based program most parents recognize immediately — the one with the CAT exam, the two years away from earning any income, and the brand name that carries weight in every boardroom in India. An 18-month analytics-focused MBA, on the other hand, is typically a shorter, more specialized program built around data analytics, business intelligence, and tech-adjacent skills, often designed to get graduates into the workforce faster with a narrower but currently high-demand skill set.
Both paths cost real money. Both come with real trade-offs. The question is which one actually recovers a ₹15 lakh-scale investment faster and more reliably.
The Real Cost of a Two-Year IIM MBA#
Let's start with the elephant in the room — IIM fees have climbed considerably over the years, and the range across India's 22 IIMs is genuinely wide. Two years at an IIM can cost as little as around ₹17.90 lakh at IIM Rohtak, or as much as ₹27.50 lakh at IIM Ahmedabad, which currently holds the position of the most expensive IIM in the country. Mid-tier legacy IIMs like Bangalore and Calcutta sit in a similar ₹26-27 lakh range.
Now here's where it gets genuinely interesting for a ₹15 lakh budget conversation specifically — newer IIMs, including institutes like Ranchi, Raipur, Kashipur, and Bodh Gaya, typically charge between ₹13 and ₹17 lakh, which fits much more comfortably within a tighter family budget. The catch is that average placement packages at these newer IIMs tend to run lower too, generally in the ₹12 to ₹18 lakh range, meaning ROI is still positive, but it typically takes two to three years to fully recover the investment rather than the faster payback top-tier IIMs can offer.
For the older, more established IIMs, the picture looks considerably stronger on paper. IIM Ahmedabad's roughly ₹27.5 lakh fee is paired with an average package reaching approximately ₹35.5 LPA, while IIM Bangalore and IIM Calcutta show similarly strong ratios, with average packages landing in the ₹34-35 LPA range against fees around ₹26-27 lakh. On the surface, that math looks genuinely compelling.
Why the Math Isn't Quite That Simple#
Here's the honest caveat every parent needs to hear before getting swept up by big average package numbers — fee years and placement years don't actually align. Institutes publish this data on different cycles, so a 2026-28 fee is often being compared against a 2023-25 placement average, meaning you're essentially comparing tomorrow's cost against yesterday's salary. The resulting ratio is indicative of the institute's general trend, not a guaranteed prediction for your child's specific outcome.
There's also the two-year opportunity cost to factor in — the salary your child isn't earning while sitting in classes for two full years, plus the emotional and financial toll of a full-time program away from home if it's not a local option. And average package figures, by definition, include some very high outliers alongside more modest offers, so the number that gets printed in glossy brochures isn't necessarily the number every single graduate actually receives.
Where the 18-Month Analytics MBA Genuinely Competes#
This is where things get relevant to your specific ₹15 lakh budget question. An 18-month analytics-focused MBA typically costs less upfront than a top-tier IIM, sits comfortably closer to that ₹15 lakh figure, and gets your child back into the workforce six months sooner than a traditional two-year program.
That six-month head start matters more than it might initially seem. It means six additional months of earning a real salary, six months of building actual work experience that compounds over a career, and six months less of interest accumulating on an education loan if you've financed the program. For families where a shorter payback window and faster re-entry into earning matters more than brand prestige, this genuinely changes the ROI calculation in meaningful ways.
The trade-off, and it's an important one, is brand weight. A shorter, specialized analytics MBA — even a genuinely rigorous one — typically doesn't carry the same instant recognition in interview rooms that "IIM" carries on a resume, particularly for roles in general management, consulting, or leadership tracks where brand pedigree still influences hiring decisions heavily.
A Practical Way to Think About This Decision#
Rather than treating this as "which is objectively better," it helps to think about which path suits your specific situation. If your family can comfortably stretch to a top-tier or mid-tier IIM specifically — the ones with average packages in the ₹30-35 LPA range — the math tends to favor going that route, since the higher long-term earning trajectory and brand-driven career mobility often outweigh the extra six months of opportunity cost.
But if your realistic budget genuinely sits closer to ₹15 lakh, and stretching further into loan territory feels financially uncomfortable, a well-chosen 18-month analytics MBA from a reputable institute can offer a faster, less financially stressful path to recovering the investment — especially if your child is specifically interested in data-driven roles where analytics skills are currently in high demand regardless of which institute's name sits on the certificate.
It's also worth remembering that many families don't pay the full fee upfront in either scenario. All IIMs offer need-based scholarships, sometimes covering up to full tuition waivers for economically weaker categories, and banks routinely offer education loans specifically structured around an IIM admission letter as collateral, generally in the 8.5% to 10% interest range with repayment starting six months after program completion. These financing options can meaningfully change which path is actually affordable for your family, so it's worth having that conversation with your bank before ruling either option out purely on sticker price.
Questions Worth Asking Before You Decide#
Before committing either way, it's worth sitting down as a family and honestly discussing a few things. What's the actual placement track record of the specific analytics MBA program you're considering, not just the general reputation of analytics MBAs as a category? Does the shorter program have a track record of graduates landing roles genuinely comparable to what the IIM route offers, or is there a meaningful gap? And realistically, how comfortable is your family with the loan amount either path requires, factoring in interest and repayment timelines rather than just the sticker price?
Final Thoughts#
There's no universally "correct" answer between an 18-month analytics MBA and a two-year IIM program — it genuinely depends on your specific budget, your child's career interests, and how much weight brand recognition carries in the field they're aiming for. What matters most is looking past glossy placement brochures and doing the real math: actual fees, realistic placement expectations for the specific institute rather than the category average, loan interest, and the genuine opportunity cost of those extra months out of the workforce.
Whichever path your family chooses, going in with clear eyes about the numbers — rather than getting swept up by prestige alone or a lower price tag alone — is what actually protects your ₹15 lakh investment and sets your child up for a recovery timeline you can both feel confident about.

Read next
Student Loan Forgiveness 2026: Who Qualifies & How to Apply
If you've spent the last year or two feeling like the rules around student loan forgiveness keep changing every time you check your email, you're not imagining it.…
Best Coding Bootcamps vs Computer Science Degree: Which Pays Off Faster?
A few years ago, a friend of mine quit her job as a restaurant manager, spent four months in an intense coding bootcamp, and landed a junior developer…
Regular MBA vs Online MBA vs Distance MBA- which is better?
You've decided to pursue an MBA. Great. Now comes the part nobody warns you about — three different formats, each with passionate defenders online, each claiming to…
How to Get a Scholarship for International Students: 2026 Guide
Picture this: you've just gotten into your dream university abroad. The excitement lasts about five minutes — until you open the fee structure and your stomach…
0 comments